Mortgage Lead Generation: The Channels That Work, Meta's Ad Rules, and a Pre-Qualification Funnel for Facebook and Instagram (2026)
Mortgage lead generation is how loan officers and brokers get home buyers and homeowners to ask about a loan. The channels compared, what the 2026 trigger lead ban changed, Meta's targeting rules for mortgage ads, and a step-by-step mobile pre-qualification funnel.
 Faheem MushtaqCo-Founder & CTO
Summarize this article with
 ChatGPT
 Claude
 Perplexity
 Grok
Mortgage lead generation is the work of getting home buyers and homeowners who need a purchase loan, a refinance or a home equity loan to ask a loan officer or mortgage broker about it. The main channels are real estate agent referrals, past clients, Google search, Facebook and Instagram ads, and bought leads from marketplaces. Referrals produce the best leads but can't be turned up on demand. Paid social can, and it is the channel where the page a borrower lands on decides whether you get a pre-qualified buyer or a phone number nobody answers.
This guide compares the mortgage lead channels, explains what changed when the trigger lead ban took effect in 2026, sets out Meta's targeting rules for mortgage ads, and walks through a mobile pre-qualification funnel screen by screen. It is written for loan officers and brokers running their own ads, and for agencies running ads for them.
Key takeaways
- Many borrowers barely shop. The CFPB wrote in May 2023 that "the plurality of borrowers only seriously consider one lender, and few borrowers consider more than two." The first lender a borrower takes seriously has a large advantage.
- Shopping is worth real money to the borrower. Freddie Mac estimated in February 2023 that getting a second rate quote could have saved a borrower as much as $600 a year in late 2022, and four or more quotes more than $1,200 a year.
- Trigger leads are restricted. The Homebuyers Privacy Protection Act, signed on 5 September 2025, stops credit bureaus selling mortgage-inquiry data to lenders without the borrower's opt-in or an existing relationship. It took effect 180 days after signing, in March 2026.
- Meta limits how you can target mortgage ads. Meta's developer documentation says Financial products and services ads must target ages 18 to 65+, all genders and at least a 15-mile radius, with no ZIP codes and no lookalike audiences.
- Mortgage leads cost more than average on Google. LocaliQ's search advertising benchmarks (updated 1 June 2026) put the Finance & Insurance cost per lead at $74.44, against $66.69 across all industries.
- Because targeting is broad, the funnel has to do the qualifying. Ask the questions that decide whether a loan officer should call, one per screen, before asking for contact details.
What is mortgage lead generation?
A mortgage lead is a person who has asked a lender, loan officer or broker to contact them about a home loan. That includes a rate quote request, a pre-qualification form, a booked call, or a calculator result they asked to have emailed.
Mortgage lead generation covers two different approaches:
An exclusive lead goes to one lender only. A shared lead goes to several, which turns every enquiry into a race to call first and a rate comparison. Generating your own leads is the only way to know every lead is exclusive.
What happened to trigger leads?
A trigger lead was data a credit bureau sold to other lenders when a consumer applied for a mortgage, which is why borrowers used to get a flood of calls the day after a credit pull. The Homebuyers Privacy Protection Act, signed on 5 September 2025, amends the Fair Credit Reporting Act to restrict this. Orrick's summary of the law says it took effect 180 days after enactment.
Credit bureaus can still furnish a trigger lead in two cases. The first is a firm offer of credit or insurance to a lender that has the consumer's authorization, originated or services their mortgage, or holds an account for them. The second is when the consumer opts in.
For a loan officer, the practical effect is that another lender's application no longer hands you a list of active borrowers. That pushes more of the work onto channels you own: referrals, your database and your own ads.
Who is looking for a mortgage right now?
The National Association of Realtors' 2025 Profile of Home Buyers and Sellers, published on 4 November 2025 and covering transactions from July 2024 to June 2025, describes the purchase market:
Two things follow for lead generation. First-time buyers are fewer and older than they used to be, so ad creative that pictures a 25-year-old first-time buyer speaks to the exception. And 88% of buyers used an agent, which is why agent partnerships matter so much for purchase loans.
How borrowers choose a lender
Borrowers rarely compare many lenders. The CFPB's May 2023 analysis of 2021 Home Mortgage Disclosure Act data found that rates across large lenders are "often around 50 basis points" apart. On a typical mortgage, the CFPB says, that gap is worth over $1,000 a year.
Even so, the same CFPB post says the plurality of borrowers only seriously consider one lender. Freddie Mac's February 2023 research found that borrowers who applied with two lenders cut their rate by an average of 20 basis points in 2022.
For a loan officer, the lesson is that being first matters, but the borrower who does shop is worth winning on clarity. A funnel that answers "could I qualify, and roughly what would I pay?" in a minute on a phone gives that borrower a reason to stop with you. Our speed-to-lead statistics cover what the research does and doesn't prove about responding first.
Mortgage lead generation channels compared
Every channel sits somewhere between high intent and high control. A borrower searching "FHA loan pre-approval near me" wants a lender today. A renter scrolling Instagram doesn't, until your ad shows them what their rent would buy.
Search and referrals capture demand that already exists. Paid social creates it from people who weren't looking yet. That is why Facebook and Instagram are the channels loan officers and their agencies reach for when the pipeline is thin, and also why those leads disappoint when the page behind the ad is a generic contact form.
What do mortgage leads cost?
Mortgage leads cost more than the average lead on Google. LocaliQ's search advertising benchmarks, last updated on 1 June 2026, report these figures:
The benchmark covers the whole Finance & Insurance category, not mortgages alone; insurance agents working from the same figure can see how it plays out in our insurance lead generation guide. LocaliQ's Facebook ads benchmarks (updated 23 September 2026) don't publish a Finance & Insurance figure for lead campaigns, so there is no comparable sourced Meta number to quote.
The number that matters is the cost per funded loan, because a cheap lead that never takes a call costs more than an expensive one that closes. For cost per lead across more industries, see our average cost per lead by industry roundup.
Meta's rules for mortgage ads
Mortgage ads on Facebook and Instagram run under Meta's special ad categories. Jon Loomer's guide to the categories (last updated 1 March 2025) lists "mortgage loans" under both Housing and Financial products and services.
Meta's Marketing API documentation says the Financial products and services category replaced the old Credit category in January 2025. The same page says these restrictions apply to Housing, Employment and Financial products and services ads:
That removes most of the levers a performance marketer would normally use to find first-time buyers. You can't target 28-to-40-year-old renters in three ZIP codes. Meta shows the ad to a broad local audience and the creative does the self-selecting.
That makes the funnel the targeting. If the ad can't choose who sees it, the questions after the click have to sort the buyer with a deposit and a timeline from the person who tapped out of curiosity.
Why mortgage Facebook ads produce bad leads
Mortgage Facebook ads don't fail because Facebook doesn't work for lenders. They fail because the page behind the ad was built for a borrower who searched, not one who scrolled.
The borrower wasn't looking for a lender. Someone who taps a "see what you could afford" ad between stories is curious, not committed. A form that asks only for name and phone collects curiosity, and the loan officer spends the day calling people who don't remember submitting.
Instant forms make submitting too easy. Meta's instant forms can prefill name, email and phone from the person's account, so one tap sends a lead. That raises volume and lowers intent. Our guide to Instagram lead ads covers when an instant form is the right call and when a website funnel gets better leads.
The landing page was built for desktop. Many lender sites send ad clicks to a long application or a "contact us" form. Zuko's 2025 industry benchmarking puts form view-to-completion at 31.3% on mobile against 37.2% on desktop. A click from the Facebook or Instagram app opens on the phone it was tapped on, so the mobile figure is the one that applies.
The form asks for too much too soon. Income, Social Security number and employer belong in the loan application, not the first screen after an ad. Our lead form guide covers which fields cost the most completions.
Nobody follows up fast enough. When the plurality of borrowers seriously consider only one lender, a lead called tomorrow has often already chosen someone else.
How to build a mortgage lead funnel for Facebook and Instagram ads
A mortgage lead funnel is a short sequence of phone-sized screens that pre-qualifies a borrower before asking for contact details. It is not a loan application. One question per screen, answered by tapping, with contact details near the end.
1. Pick one offer per campaign
The offer is what the borrower gets for tapping. Match it to the ad and run one offer per campaign:
A first-time buyer guide is a lead magnet, not a loan offer. Our lead magnet funnel guide covers how to build one that hands warm leads to a loan officer later.
2. Ask the questions that decide the call
Every question should change who calls, what they say, or whether anyone calls at all. Useful pre-qualification questions:
- What are you looking to do? (Buy my first home, Buy my next home, Refinance, Take cash out)
- When are you hoping to buy? (Within 3 months, 3–6 months, 6–12 months, Just exploring)
- Have you found a home or an agent yet? (Found a home, Working with an agent, Not yet)
- What price range are you looking at? (Four or five tap ranges for your market)
- How much have you saved for a down payment? (Ranges, including "Not sure yet")
- How would you describe your credit? (Excellent, Good, Fair, Not sure)
- Are you a veteran or active-duty service member? (Yes, No), so VA-eligible borrowers get the right conversation
Each of those is a tap. Tap-to-answer questions keep a phone visitor moving, and each answer is captured as they go, so you learn which question loses people. Our guide to multi-step forms covers why this order beats one long form.
3. Branch on timeline and readiness
A borrower buying within three months who has an agent should see a loan officer's calendar. A renter "just exploring" with nothing saved should get the first-time buyer guide and a follow-up sequence, not a sales call they'll ignore. Send each to a different ending.
That routing is the difference between a funnel and a form. Our lead qualification guide covers how to score answers so the readiest borrowers get called first.
4. Ask for contact details last, with clear consent
By the time a borrower has answered six questions, asking for a name, email and mobile number feels like the obvious next step. Ask for them on one screen and say exactly why ("so your loan officer can send your numbers"). Put consent to be contacted by phone and text on that screen in plain words, and have your compliance team approve the wording.
Then offer a calendar slot on the next screen. A borrower who books a 15-minute call has committed more than one who typed a number.
5. Watch your advertising disclosures
Mortgage ads are regulated. Under Regulation Z, section 1026.24(d), stating a down payment, the number of payments, a payment amount or a finance charge in an ad triggers further disclosures, including the APR. A funnel screen that says "own for $1,800 a month" counts. This guide isn't legal advice: have compliance review the ad and every funnel screen before launch.
6. Send the lead where the loan officer works, immediately
Route every submission to wherever the loan officer already works: a Slack channel, a shared Google Sheet, or the loan origination system or mortgage CRM through a webhook. The answers should arrive with the lead, so the first call opens with "you're looking at homes around $350,000 in the next three months" rather than "what can I help you with?"
7. Tell Meta which leads were good
Install the Meta Pixel and the Conversions API so Meta sees submissions that browser privacy settings would otherwise hide. Then send the conversion event for qualified leads, not for every submit. Our Meta Conversions API guide covers which events a lead funnel should send. With age, gender and lookalike targeting off the table, the conversion signal is one of the few ways left to steer who Meta shows the ad to.
Worked example: a first-time buyer pre-qualification funnel
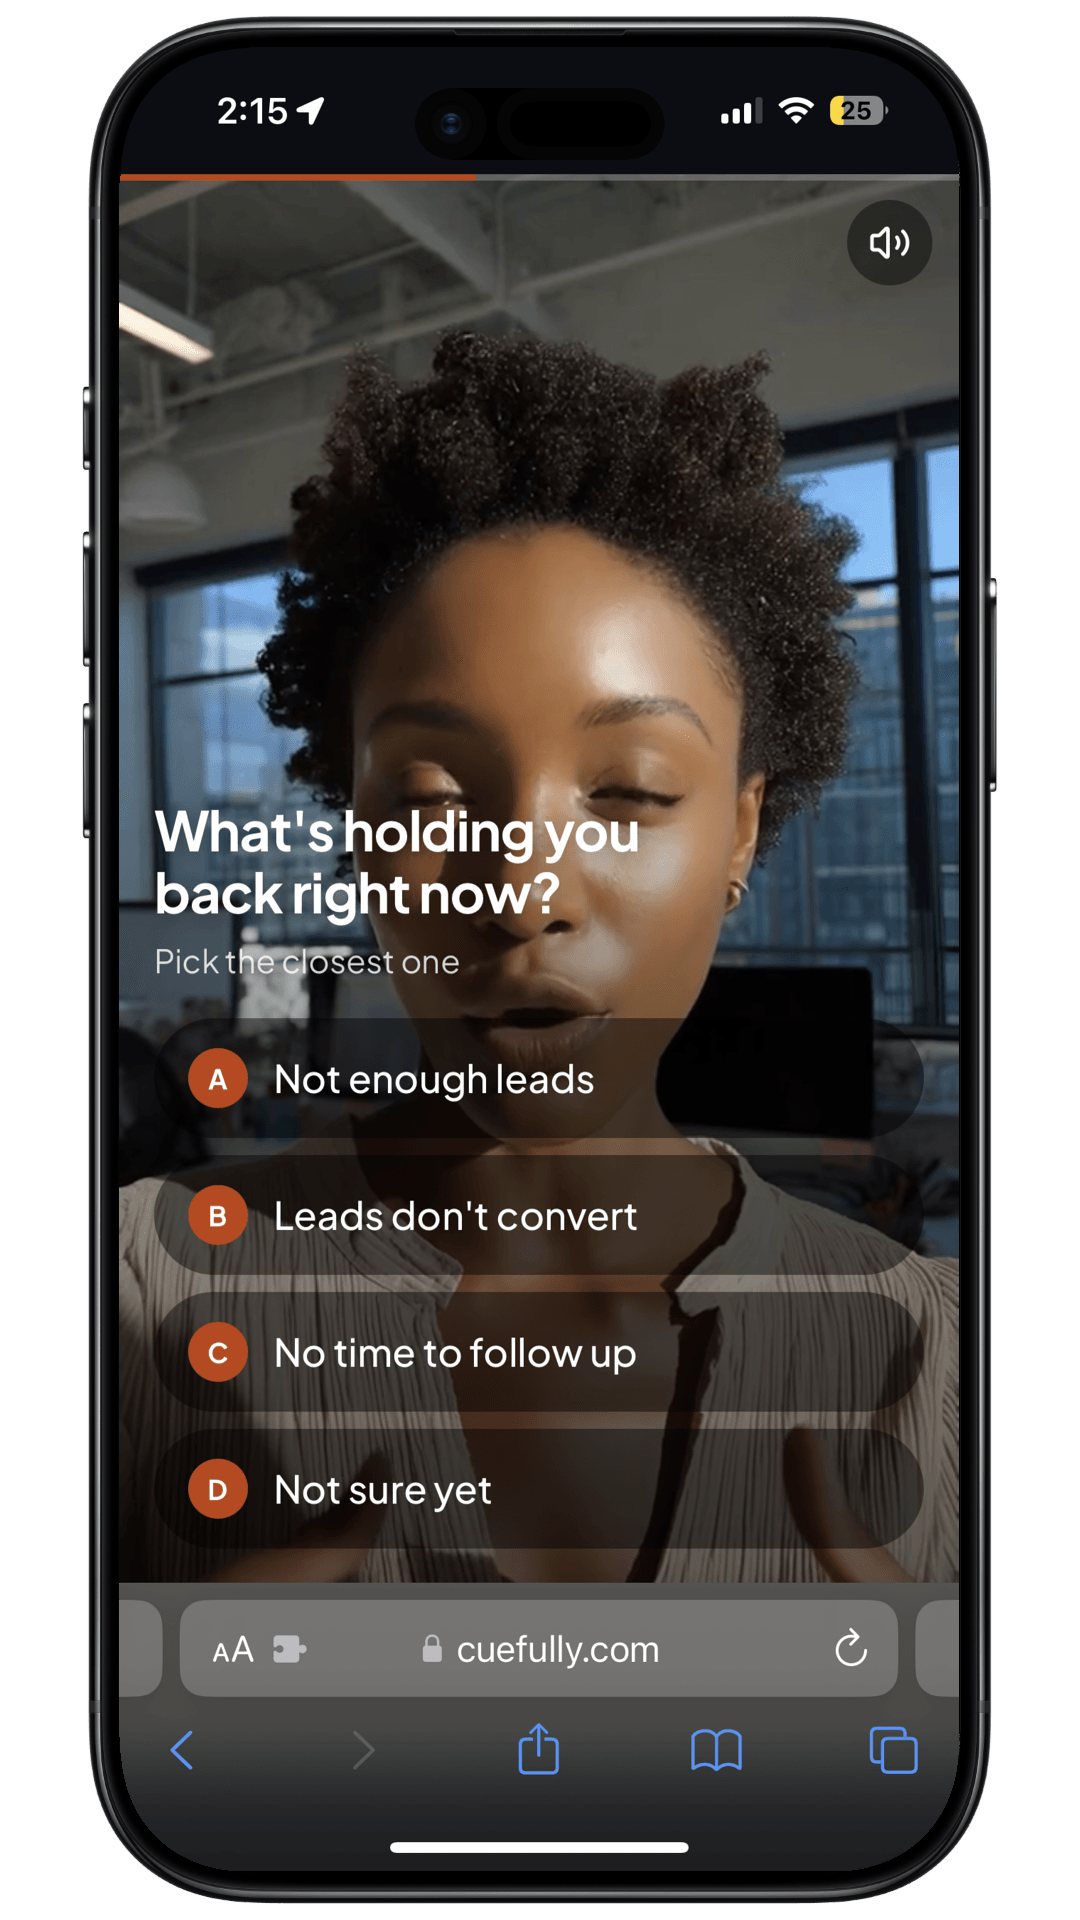
Here is a funnel for a loan officer running a first-time buyer campaign on Instagram. It is illustrative and reports no results.
The qualifying funnel that books good fits and sends everyone else a guide is this exact shape: three qualifying questions, a call for ready leads and a free guide for early-stage ones. A loan officer can copy its structure and swap the questions for the ones above.
For a softer top-of-funnel campaign, a scored money personality quiz builds an email list of people thinking about their finances, which a loan officer can nurture until they're ready to buy.
For an agency running ads for several loan officers or brokerages, each client's funnels, leads and brand kit should live in its own workspace, so one lender's borrowers never appear in another's dashboard. Our guide to choosing a funnel builder as an agency covers what to check.
How to measure mortgage lead generation
Cost per lead is the number everyone reports and the one that misleads most. Track the whole chain:
Then look at drop-off per funnel step. If 40% of visitors leave on the credit question, the question or its wording is the problem, not the ad. Per-step analytics show which screen costs you the lead.
Frequently asked questions
What is the best way to get mortgage leads? Real estate agent referrals and past clients bring the highest-quality mortgage leads, and 88% of buyers in NAR's 2025 Profile used an agent. To grow beyond referrals, combine Google search for borrowers looking now with Facebook and Instagram ads for those who aren't looking yet, and send ad traffic to a pre-qualification funnel.
Do Facebook ads work for loan officers? Yes, when the ad sends borrowers to a funnel that pre-qualifies them and books a call. Meta's targeting rules for mortgage ads are broad, so the funnel's questions, branching and fast follow-up do the qualifying the targeting can't.
Can I target first-time buyers with mortgage ads on Facebook? Not by age, ZIP code or lookalike audience. Meta's rules for Financial products and services ads fix age at 18 to 65+, require at least a 15-mile radius and remove lookalikes. Target first-time buyers through the creative and the offer instead, and let the funnel sort them.
How much does a mortgage lead cost? It depends on the channel and how you define a lead. LocaliQ's 2026 search advertising benchmarks put the Google Ads cost per lead for Finance & Insurance at $74.44. Measure cost per funded loan rather than cost per lead.
Are trigger leads still legal? Only in limited cases. Since the Homebuyers Privacy Protection Act took effect in March 2026, credit bureaus can furnish trigger leads only with the consumer's opt-in, or as a firm offer to a lender with an existing relationship or the consumer's authorization.
Should I buy mortgage leads or generate my own? Bought leads are fast to start but are often shared with other lenders. Generated leads take longer to set up but are exclusive to you. Many loan officers buy leads to fill gaps and invest in their own channels for the long term.
What questions should a mortgage lead form ask? Ask the loan goal, timeline, whether they have an agent or a home, price range, down payment saved and a self-reported credit band, then contact details with consent. Leave income, employer and Social Security number for the loan application.
Sources and method
Sources were checked on 12 November 2026. The worked example is illustrative and reports no conversion results. This guide is not legal advice.
- CFPB — "Mortgage data shows that borrowers could save $100 a month (or more) by choosing cheaper lenders" (Alexei Alexandrov and Elizabeth Saunders, 24 May 2023) — "the plurality of borrowers only seriously consider one lender"; price dispersion "often around 50 basis points"; over $1,000 a year for a typical mortgage. Based on 2021 HMDA data.
- Freddie Mac — "When Rates Are Higher, Borrowers Who Shop Around Save More" (16 February 2023) — two quotes up to $600 a year and four or more quotes over $1,200 a year (October–November 2022); two-lender applicants cut their rate by an average of 20 basis points in 2022.
- NAR — "First-Time Home Buyer Share Falls to Historic Low of 21%, Median Age Rises to 40" (4 November 2025) — 2025 Profile of Home Buyers and Sellers: first-time share 21%, median age 40, down payments 10% and 23%, 30% of repeat buyers paid cash, 88% used an agent.
- Orrick InfoBytes — "President Trump signs Homebuyers Privacy Protection Act restricting mortgage trigger leads" (9 September 2025) — signing date, the 180-day effective date and the exceptions.
- Meta for Developers — Special Ad Categories — Financial products and services replacing Credit; age, gender, 15-mile radius, ZIP code, detailed targeting and lookalike restrictions.
- Jon Loomer — "Special Ad Categories: A Guide for Meta Ads" (last updated 1 March 2025) — "mortgage loans" listed under both Housing and Financial products and services. A summary, not Meta's policy text.
- LocaliQ — "Search Advertising Benchmarks" (Stephanie Heitman, last updated 1 June 2026) — Finance & Insurance cost per lead $74.44, conversion rate 2.64%, CPC $3.39, CTR 9.83%; all-industry averages.
- LocaliQ — "Facebook Ads Benchmarks" (Susie Marino, last updated 23 September 2026) — checked for a Finance & Insurance lead-campaign figure; none is published.
- Zuko — "Average Conversion Rate Statistics by Industry 2025" — form view-to-completion by device: desktop 37.2%, mobile 31.3%.
- CFPB — Regulation Z, 12 CFR 1026.24 — triggering terms in closed-end credit advertising and the disclosures they require.
- CueFully templates — the video lead qualification and money personality quiz funnel steps, as published on their template pages.
Running mortgage ads to a long application form? Try a qualifying funnel on your phone — then start free with CueFully.
Build from the guide
Start with the Video Lead Qualification Funnel template
Start from a complete mobile-first flow, customize it for your client, and publish a funnel that captures qualified leads without adding developer work.